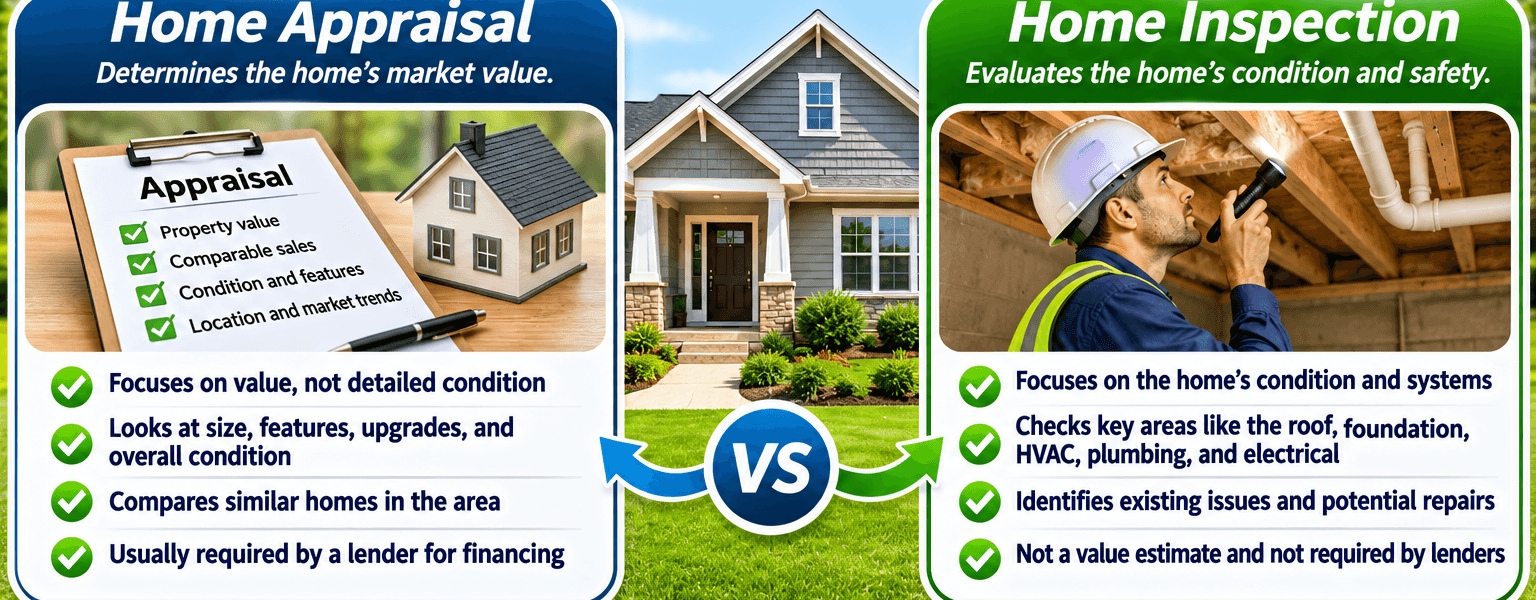
What Home Appraisers Look At, and How It Differs From a Home Inspection
A home appraisal is an independent opinion of a property’s market value, usually ordered by a lender during a purchase or refinance. Appraisers consider the home’s size, condition, features, location, and recent comparable sales. A home inspection is different: it examines the condition of systems and components and does not set value.
Understanding what appraisers review helps homeowners and buyers prepare and interpret results.
What Appraisers Evaluate
- Size, layout, number of bedrooms and bathrooms, and lot size.
- Condition, updates, and quality of construction.
- Location factors, such as neighborhood and nearby amenities.
- Recent comparable sales of similar homes nearby.
- Market trends affecting supply and demand.
Personal decor and furniture generally do not affect value, but obvious maintenance issues can.
Appraisal vs. Inspection
Appraisals focus on value for the lender and buyer, while inspections focus on condition for the buyer. Inspectors look closely at roofing, electrical, plumbing, heating, and structural components and report defects. Appraisers may note visible condition issues that affect value or lending requirements but do not perform a full inspection.
Federal rules require appraiser independence in many mortgage transactions, meaning lenders and agents cannot pressure appraisers to reach a specific value.
Preparing for an Appraisal
Make the home easy to access, including attics, basements, and garages. Prepare a short list of improvements with dates and costs, such as a new roof, updated kitchen, or replaced heating system, along with permits when available. Fix obvious maintenance issues, such as broken handrails or missing smoke detectors, which can affect lending requirements.
Clean, uncluttered spaces make it easier for the appraiser to measure and photograph the home accurately.
Keep a copy of past appraisals and improvement records, which can help future appraisers understand the home’s history. Organized records save time later.
If the Appraisal Comes in Low
Review the report for factual errors, such as wrong square footage or missing features. Buyers and sellers can provide additional comparable sales through the lender, which may request a reconsideration of value. Options include renegotiating the price, increasing the down payment, or ordering a second appraisal if allowed.
For estate, divorce, or pre-listing valuations, licensed appraisers on Huddle Directory can be compared by credentials and turnaround times. Homeowners seeking pre-listing or estate appraisals can compare credentials and turnaround times there.
Value and Condition Are Different Questions
Appraisers estimate market value using size, condition, location, and comparable sales, while inspectors assess a home’s systems and defects. Review appraisals for errors, use the lender’s reconsideration process when needed, and use Huddle Directory to compare licensed appraisers for non-lending needs.
Frequently asked questions
Who orders the appraisal in a home purchase?
In most mortgage purchases, the lender orders the appraisal, often through an appraisal management company, to support appraiser independence. The buyer usually pays the appraisal fee. Homeowners can also order private appraisals for other purposes, such as estates or pre-listing pricing.
Can I be present during the appraisal?
Homeowners or sellers can often be present and may share a list of recent upgrades. Avoid pressuring the appraiser about value. Providing accurate information about improvements, permits, and features can help the appraiser complete a thorough report. Share upgrades with documentation.
What is a reconsideration of value?
It is a request, usually made through the lender, asking the appraiser to review additional information, such as comparable sales or factual corrections. The appraiser decides whether the information changes the value. Rules and processes vary by lender. Provide comparable sales through the lender.
Does a home inspection affect the appraisal?
Not directly. Inspections are separate and usually for the buyer's benefit. However, serious condition issues found by either professional may affect negotiations, lending requirements, or value. Buyers often schedule both during the purchase process. Both reports serve different purposes. Many buyers schedule both early.

Admin
The huddledir.com editorial team shares practical ideas for local businesses and the communities that support them.